I usually don't look at the stats for my blog, but I have noticed that 50% of blog audience is from the US and I am getting a lot of page views from people in other parts of the world. So to all of you I say WELCOME!!!
I was extremely happy to see that a large portion of blogs audience is from Vietnam (25%), India (5%), Ukraine(3%), Russia (3%), UAE(1%), China (10%), Hong Kong (5%) and Iran (1%) to be reading my blog!
I would love it if you would post some comments and we could interact.
best wishes to all!
Monday, March 07, 2011


SLV Update
This maybe the day to take some profit in Silver, this is a big volume day so far and we could correct for a few days back down to the 33-32 range on the SLV. I went long ZSL (double short Silver) this morning, a small position as a hedge as I had sold have my position a day too early as usual.


As for the S&P as I mentioned the other day the character of the market has changed. Buying the dip is not working anymore. I would be loathe be long at this time, we probably will test 1294 before we test 1332, and not so sure it will hold this time.
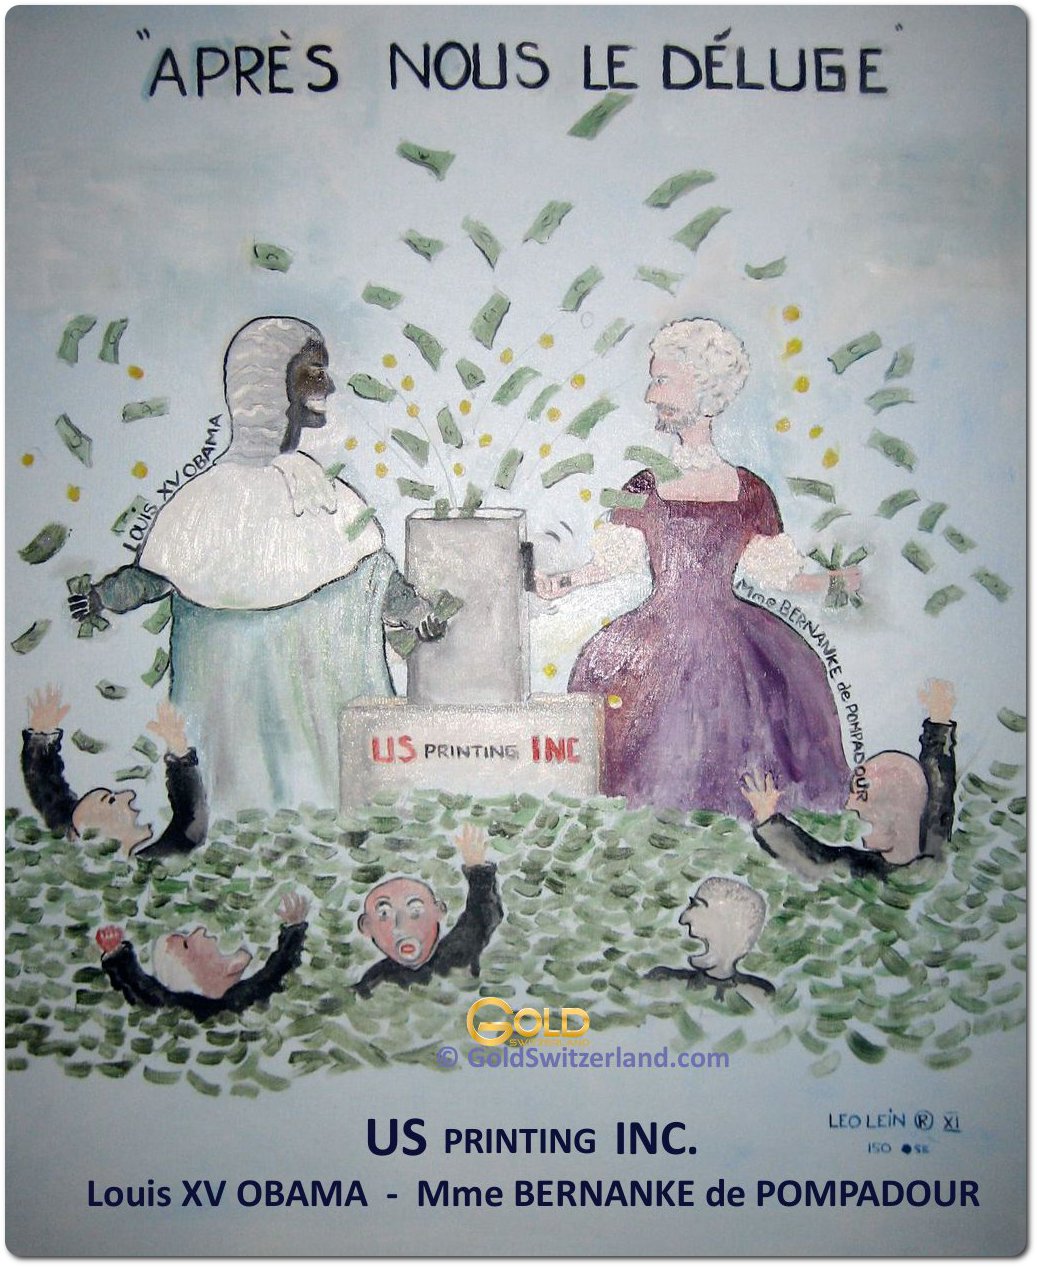
Brilliant Post, A Must Read; APRES NOUS LE DELUGE by Egon von Greyerz
Happy days are here again! Stock markets are strong, company profits are up, bankers are making record profits and bonuses, unemployment is declining, and inflation is non-existent. Obama and Bernanke are the dream team making the US into the Superpower it once was.
Yes, it is amazing the castles in the air that can be built with paper money and deceitful manipulation of all economic data. And Madame Bernanke de Pompadour will do anything to keep King Louis XV Obama happy, including flooding markets with unlimited amounts of printed money. They both know that, in their holy alliance, they are committing a cardinal sin. But clinging to power is more important than the good of the country. An economic and social disaster is imminent for the US and a major part of the world and Bernanke de Pompadour and Louis XV Obama are praying that it won’t happen during their reign: “Après nous le déluge”. (Warm thanks to my good friend the artist Leo Lein).
Yes, it is amazing the castles in the air that can be built with paper money and deceitful manipulation of all economic data. And Madame Bernanke de Pompadour will do anything to keep King Louis XV Obama happy, including flooding markets with unlimited amounts of printed money. They both know that, in their holy alliance, they are committing a cardinal sin. But clinging to power is more important than the good of the country. An economic and social disaster is imminent for the US and a major part of the world and Bernanke de Pompadour and Louis XV Obama are praying that it won’t happen during their reign: “Après nous le déluge”. (Warm thanks to my good friend the artist Leo Lein).
S&P Recap, a look ahead

This was just slightly below the consensus estimates for an increase of 198,000 (Manufactured). The January totals were revised higher to 58K from 36K and the combination of revisions for January and December produced an increase of 58K jobs. The private sector showed gains of 222K jobs (lie some more), which again was above the estimates. The Unemployment Rate was once again a big surprise as it fell to 8.9% (Really?!?), which was below the expectations for a reading of 9.1% and January’s level of 9.0%. Although stock futures initially rallied on the jobs report, crude's continued rude rise pushed prices lower as the open approached.

Friday's session began quietly without a significant gap. But sellers were waiting and the first half hour was gently downhill. Then at 10:00 am the action escalated and the selling picked up. The following thirty minutes gave up eight points before the SPX stabilized and tried to rally back. After oscillating up and down and back up about four points over seventy-five minutes the index rolled over almost twelve points in a half hour. This was essentially the low of the session but it was tested several times later in the day. But the last thirty minutes saw a ferocious ten point recovery as the index exploded upward to close near the midpoint of the intraday range.
As we go into trade today remember that 1332 level that we hit last Tuesday and could not take out on Thursday and Failed Friday as well. If I was long the SPY (S&P ETF) its time to be very cautious. These gyrations are a part of an extended bull run coming to a close. Initially, the mind that has been trained by the markets goes into a state of denial, refusing to admit that its over. But then sadistically teased by the big up moves that invite in more money for fear of missing out, only to be left hanging in misery.
If I were bullish on US equities at these levels which I am not, I would wait for the market to take out 1332. There is too much downside risk right now, especially given the political environment.
Declining volume was higher at a ratio of 3.13 to one. The closing TRIN was 1.85 and the final tick was 407. The five day average of TRIN is 1.43 and the ten day average of TRIN is 1.32. The NYSE Composite Index lost -0.62% today while the SPX lost -0.74%.
For the NYSE, relative to the previous 30 session average, volume was -1.94% below the average. Of the last 15 sessions 7 sessions ended with volume greater than the previous rolling 30 day average volume. Of the last 30 sessions, 24 sessions ended on a positive tick, 7 of last 10. For the SPX, the day's volume was 101.9% of the average daily volume for the last year. Volume was 97.6% of the last 10 day average and 103.5% of the previous day’s volume.
Breadth was negative as would be expected on a down day and negative volume was even more negative than issues.
Total tick for the day was -193,000 and the average tick for the day was -124. There were 60 ticks greater than 600 and 162 ticks more extreme than -600. There were 8 ticks greater than 1000 and 12 ticks more extreme than -1000. The tick action suggests institutional distribution.
Clearly the big volume spike Friday was with the index breakdown midday. The late data rally, on the other hand, was on falling volume.
Sectors Performance or Friday:
- Basic Materials -- Outperformed the SPX by +1%.
- Energy -- Outperformed the SPX by +4%.
- Consumer Staples -- Outperformed the SPX by +31%.
- Utilities -- Outperformed the SPX by +14%.
- Health Care -- Outperformed the SPX by +61%.
Sectors weaker than the SPX for Friday:
- Financials -- Underperformed the SPX by -48%.
- Industrials -- Underperformed the SPX by -42%.
- Technology -- Underperformed the SPX by -6%.
- Consumer Discretionary -- Underperformed the SPX by -1%.
- Basic Materials -- Outperformed the SPX by +1%.
- Energy -- Outperformed the SPX by +4%.
- Consumer Staples -- Outperformed the SPX by +31%.
- Utilities -- Outperformed the SPX by +14%.
- Health Care -- Outperformed the SPX by +61%.
Sectors weaker than the SPX for Friday:
- Financials -- Underperformed the SPX by -48%.
- Industrials -- Underperformed the SPX by -42%.
- Technology -- Underperformed the SPX by -6%.
- Consumer Discretionary -- Underperformed the SPX by -1%.
Subscribe to:
Posts (Atom)